MAJORITY: Mobile banking

Screenshots
Details
- Rating
- 12.00K reviews
- Version
- 5.14.0
- Developer
- MAJORITY USA, LLC
Analysis by Norviv
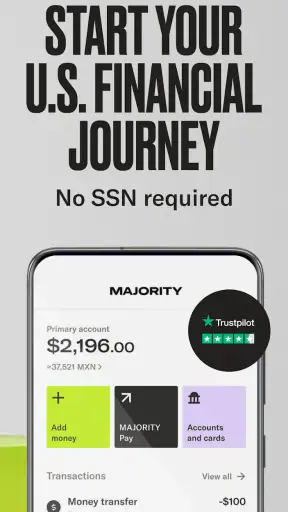
I approached MAJORITY as a practical mobile banking app rather than just another money-transfer tool. Its main appeal is clear: it brings a US account and debit card into one mobile experience, with options aimed at people who need to send money home, manage everyday spending, and work toward building credit without relying on a Social Security number. That combination gives it a more focused identity than a traditional bank app.
In my experience, the app makes the most sense for newcomers to the United States, international workers, families supporting relatives abroad, and anyone who wants a straightforward financial starting point. It is free to download, rated for Everyone, and developed by MAJORITY USA, LLC. The service has grown to more than a million installs, with a 4.7 average from roughly twenty-three thousand ratings, so it is clearly being used by a substantial audience rather than serving only a narrow experiment.
That said, I would not treat it as a universal replacement for every bank. Its value depends heavily on what you need from a financial app. If your priority is a broad investment platform, complex budgeting, or a long-established full-service bank relationship, another option may suit you better. If your priority is access, remittances, and a mobile-first account, the picture is much more interesting.
How the app feels during ordinary banking tasks
I focus on the small decisions that make everyday banking feel manageable: checking the account before spending, keeping transfer money separate in my own budget, and taking a moment to verify details before confirming an action. Those habits matter especially when one app serves both local purchases and support for family abroad. Next, I look at how that mix shapes the app’s practical day-to-day workflow.
Speed expectations when you are checking money or starting a transfer
The first thing I look for in a finance app is not flashy design but how quickly I can reach the useful part of the service. With MAJORITY, the important workflow is easy to understand: open the app, review the account, use the debit card, or begin a money movement task. That direct structure matters because financial apps are often opened for a single urgent reason, such as checking whether a payment arrived or confirming that there is enough available for a purchase.
I would describe the experience as focused rather than overloaded. The app is built around a US account, debit-card use, sending money home, and credit-building goals. Those priorities help reduce the feeling of wandering through unrelated banking products. For someone who has never used a US financial account before, a narrower set of choices can be less intimidating than the crowded navigation found in a major bank application.
There is also a practical speed advantage in having these needs gathered in one place. A user who regularly supports relatives abroad does not need to move between a bank app, a separate remittance service, and another tool for card activity. That does not mean every transaction will complete instantly; transfer timing and account processes can depend on the specific operation. It does mean the path from opening the app to finding the relevant action feels more purposeful than a general-purpose financial dashboard.
Stories Picked for You

Life360 Works Better When Your Household Agrees on What to Share

YouVersion Bible Fits Scripture into Everyday Phone Routines

Matchington Mansion Review: Match-Three Puzzles With a Place to Restore

Android Auto Shows Why Safer Driving Software Does Less

Google Find Hub Runs on Shared Devices and Quiet Trust

Sygic GPS Navigation: The Ultimate Offline Travel Companion
My advice is to set up the account when you are calm, not during an emergency. Complete the identity and account steps carefully, make sure your contact details are current, and learn where the card and transfer controls are before you need them. A few minutes of preparation can make the app feel considerably faster later, especially when you are dealing with a time-sensitive payment.
What happens during heavier use
MAJORITY is most useful when several financial needs overlap. Imagine a worker who receives money into a US account, uses a debit card for groceries, and sends part of the balance to family overseas. That person may open the app several times in one day, switching between account information, card-related actions, and international support. The advantage is continuity: the same service remains the central place for those tasks.
Heavy use also exposes the trade-off behind a focused finance app. Concentrating multiple responsibilities in one account is convenient, but it makes organization important. I recommend separating routine spending from money intended for a transfer whenever possible. That simple habit makes the available balance easier to interpret and reduces the chance of spending funds that were mentally reserved for someone else.
Another useful workflow is to check the account before beginning a transfer rather than assuming the balance is sufficient. This sounds obvious, but it is especially important when card purchases and family support happen close together. A mobile banking app can make actions feel immediate, while the user still needs to think through the order of payments and the amount that should remain available.
The credit-building angle also deserves realistic expectations. Having a feature aimed at building credit can be valuable for someone establishing a financial history, but it should not be treated as a shortcut. Responsible use, awareness of obligations, and regular account management still matter. I would view this part of MAJORITY as a reason to consider the app, not as a promise that every user will see the same outcome.
Reliability and the importance of recovery habits
Reliability in banking is more than whether an app opens quickly. I want confidence that I can identify my balance, understand what action I am taking, and recover sensibly if something does not go as expected. MAJORITY’s focused purpose helps with the first two points because the app is not trying to be an entire financial marketplace. The account, card, remittance, and credit-building themes are easy to connect to everyday decisions.
Still, no mobile banking experience should be treated as a substitute for careful records. Before sending money home, I would review the recipient details and the amount slowly, especially if the transfer is important to a family member. Save confirmation information in a secure place and avoid repeating the action simply because the screen takes longer than expected. In financial apps, impatience can create duplicate requests or unnecessary confusion.
Recovery is another area where user habits matter. Keep access information private, use the official app installation route, and make sure the phone number or email associated with the account remains reachable. If you change phones, do not discard the old device until you are confident that you can sign in and complete any required security steps on the new one. These are not glamorous tips, but they are more useful than judging a banking app only by its opening animation.
I also recommend treating the debit card as a separate responsibility within the same service. If the card is misplaced, act promptly through the available account controls rather than waiting to see whether it turns up. Review activity regularly, particularly after travel or frequent purchases. The app’s value depends on users noticing unusual activity early, not merely on having a convenient card attached to an account.
Device constraints and everyday practicality
The app supports devices running iOS or Android versions from 9 onward, which gives it a broad compatibility range for people who are not using the newest phone. That matters for the audience MAJORITY is trying to serve. A person opening a US account after moving countries may be relying on an older but functional handset, and excluding that user with demanding hardware requirements would undermine the app’s accessibility.
On an older phone, I would keep expectations sensible. Finance apps need to protect account information and handle network communication, so a slower device or unstable connection can make any banking task feel less immediate. Avoid starting an important transfer while switching between many demanding apps, and keep enough free storage for normal updates. These steps are particularly helpful when the phone is also used for messaging relatives, work, navigation, and document tasks.
MAJORITY is not the kind of app I would install casually on a device shared by many people. A banking account deserves a personal phone with a screen lock and sensible privacy settings. If you must use a shared or borrowed handset, I would be much more cautious about account access, saved credentials, and leaving the session open.
Resource demands are difficult to judge from the app’s purpose alone, but a mobile banking service generally earns its place by handling short, purposeful sessions rather than keeping the screen active all day. I would use it to check an account, manage a card, or arrange a transfer, then close it. That usage pattern is also better for privacy and battery life than leaving financial software running unnecessarily.
Where it stands against ordinary alternatives
A conventional bank app may offer a wider selection of products, including established bill-payment tools, savings structures, lending options, and more extensive account history. That breadth can be valuable if you already have a long-term banking relationship or want all financial products under one institution. It can also make the experience feel complicated for someone whose immediate needs are simply receiving money, using a debit card, and supporting family abroad.
A standalone remittance service may be preferable for a person who only sends money internationally and does not need a US account or debit card. Such a service can keep the purpose narrow. The trade-off is that it will not necessarily provide the same combined account-and-card experience that makes MAJORITY appealing.
Digital wallets can be convenient for purchases, but they are not always designed around the realities of establishing a US financial base. MAJORITY’s specific focus on a US account without an SSN, together with its credit-building direction, gives it a different role. I would choose it when access and consolidation matter more than having the broadest possible banking catalog.
The best comparison is therefore not “which app has the most features?” It is “which service matches the way I actually move money?” For a user who needs international support and a debit card in the same mobile relationship, MAJORITY has a coherent advantage. For someone seeking advanced financial planning, investing, or a complete household banking suite, a traditional institution may remain the stronger primary choice.
Who will benefit most from the account
I see the strongest fit among people who are building their financial routine in the United States. The ability to work with a US account without an SSN can remove a major barrier for users who are new to the country or whose circumstances do not fit the usual onboarding path. That does not make the app suitable for every person, but it addresses a very specific and meaningful problem.
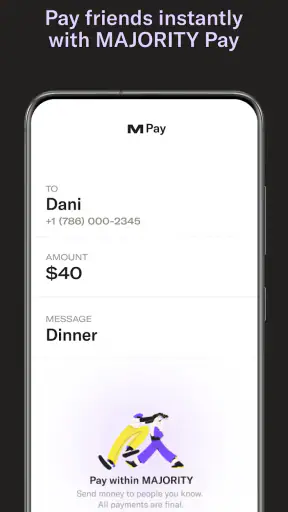
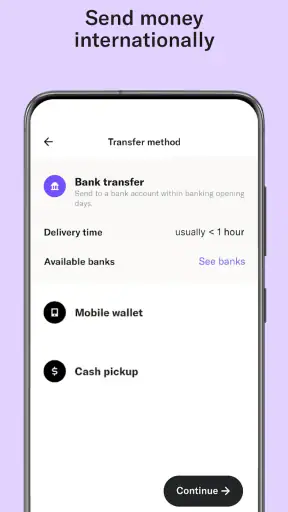
It can also suit families with regular cross-border responsibilities. Instead of treating money sent home as an occasional separate chore, the user can make it part of the same monthly routine as checking available funds and using a debit card. I would still compare the actual terms and timing of any transfer before committing to a large amount, because convenience should not replace attention to the transaction details.
People interested in building credit may also find the app worth exploring. The important point is to use that feature deliberately. Start with manageable activity, understand what you are agreeing to, and avoid treating credit-building as permission to spend beyond your means. The app can support a financial plan, but it cannot create good financial habits on its own.
Who should choose something else
I would hesitate to recommend MAJORITY as the only financial app for someone who needs sophisticated categorization, multiple account types, investing, or detailed long-term planning. A larger bank or a dedicated budgeting platform may provide more depth for those jobs. Likewise, someone who never sends money abroad and already has a satisfactory US account may gain little from switching.
It is also not the best choice for a user who wants to avoid all mobile-first account management. The app’s strengths come from putting the relationship on a phone. If you prefer extensive branch support or face-to-face assistance for routine banking, a conventional bank may feel more comfortable.
Finally, users should not select it solely because it is free. Free access is attractive, but the right decision still depends on how the account, card, transfers, and credit-building tools fit personal needs. I would read each relevant screen before confirming an action and keep the app as one part of a broader money-management routine.
My performance verdict after using it as a daily finance tool
MAJORITY works best when I judge it by its intended job: making core US banking and international money support more approachable from a phone. Its focused design can make ordinary actions feel less cumbersome than they do in a large, product-heavy bank app. The combination of account access, debit-card use, sending money home, and credit-building support gives it a clear audience and a practical reason to exist.
The performance story is less about raw speed than about reducing unnecessary steps. On a compatible phone with a stable connection, the app should be approached as a short-session tool: open it for a specific financial task, verify the details, complete the action carefully, and leave with a clear record of what happened. That workflow is efficient and reduces the risk of careless repeated actions.
Its limitations are equally clear. It cannot replace the breadth of a full-service bank for every user, and no app can remove the need to check balances, protect access, and think carefully about transfers. Older devices and weak connections may make urgent tasks feel slower, while users with complex financial needs may quickly outgrow the focused feature set.
MAJORITY is currently at version 5.14.0 and has been available since April 26, 2019, giving it a longer presence than a brand-new finance product. With a free price and an Everyone age rating, it is easy to consider, especially for users who need a US account and debit card without an SSN. My recommendation is positive but specific: choose MAJORITY when accessible US banking and sending money home are central to your routine. If those needs do not describe you, a traditional bank or a specialist service may be the more efficient and dependable fit.
Frequently Asked Questions
01What is MAJORITY, and who is the mobile banking service designed for?
MAJORITY is a mobile banking service created primarily for immigrants, international families, and people who need convenient tools for managing money across borders. After signing up through the app, users can typically access banking features, a debit card, money transfer options, and other services in one place. Availability and eligibility may depend on your country, identity verification, and current MAJORITY policies.
02How do I open a MAJORITY account, and what documents are required?
Opening an account is handled through the MAJORITY mobile app and normally involves entering personal information, creating login details, and completing identity verification. You may be asked to provide a government-issued identification document, proof of address, and additional information required by financial regulations. Approval is not always instant, so make sure your details are accurate and that your documents are valid and clearly readable.
03Does MAJORITY provide a physical debit card, and where can I use it?
MAJORITY generally offers a debit card connected to the account, allowing users to make purchases and access available funds wherever the card network is accepted. The app can be used to review transactions, monitor spending, and manage card-related settings. Before relying on the card for travel or cash withdrawals, check current fees, supported locations, usage limits, and delivery requirements in your region.
04Can I send money internationally or transfer funds to family members with MAJORITY?
One of MAJORITY’s main attractions is its focus on helping users send money and support family members, including international transfer functionality where available. Transfer speed, supported countries, exchange rates, fees, and recipient requirements can vary depending on the destination and the selected service. Review the complete cost and delivery estimate inside the app before confirming a transaction, especially for urgent transfers.
05Is MAJORITY safe, and what should I know about fees and customer support?
MAJORITY uses account security measures such as identity verification, login protection, and transaction monitoring, but users should still protect their password, phone, and verification codes. The service may charge fees for certain plans, transfers, card services, or cash-related transactions, while some features may require a subscription. Check the current pricing page and contact in-app support if you notice an unfamiliar transaction or account problem.


